 Locations
 Treasury
 Login


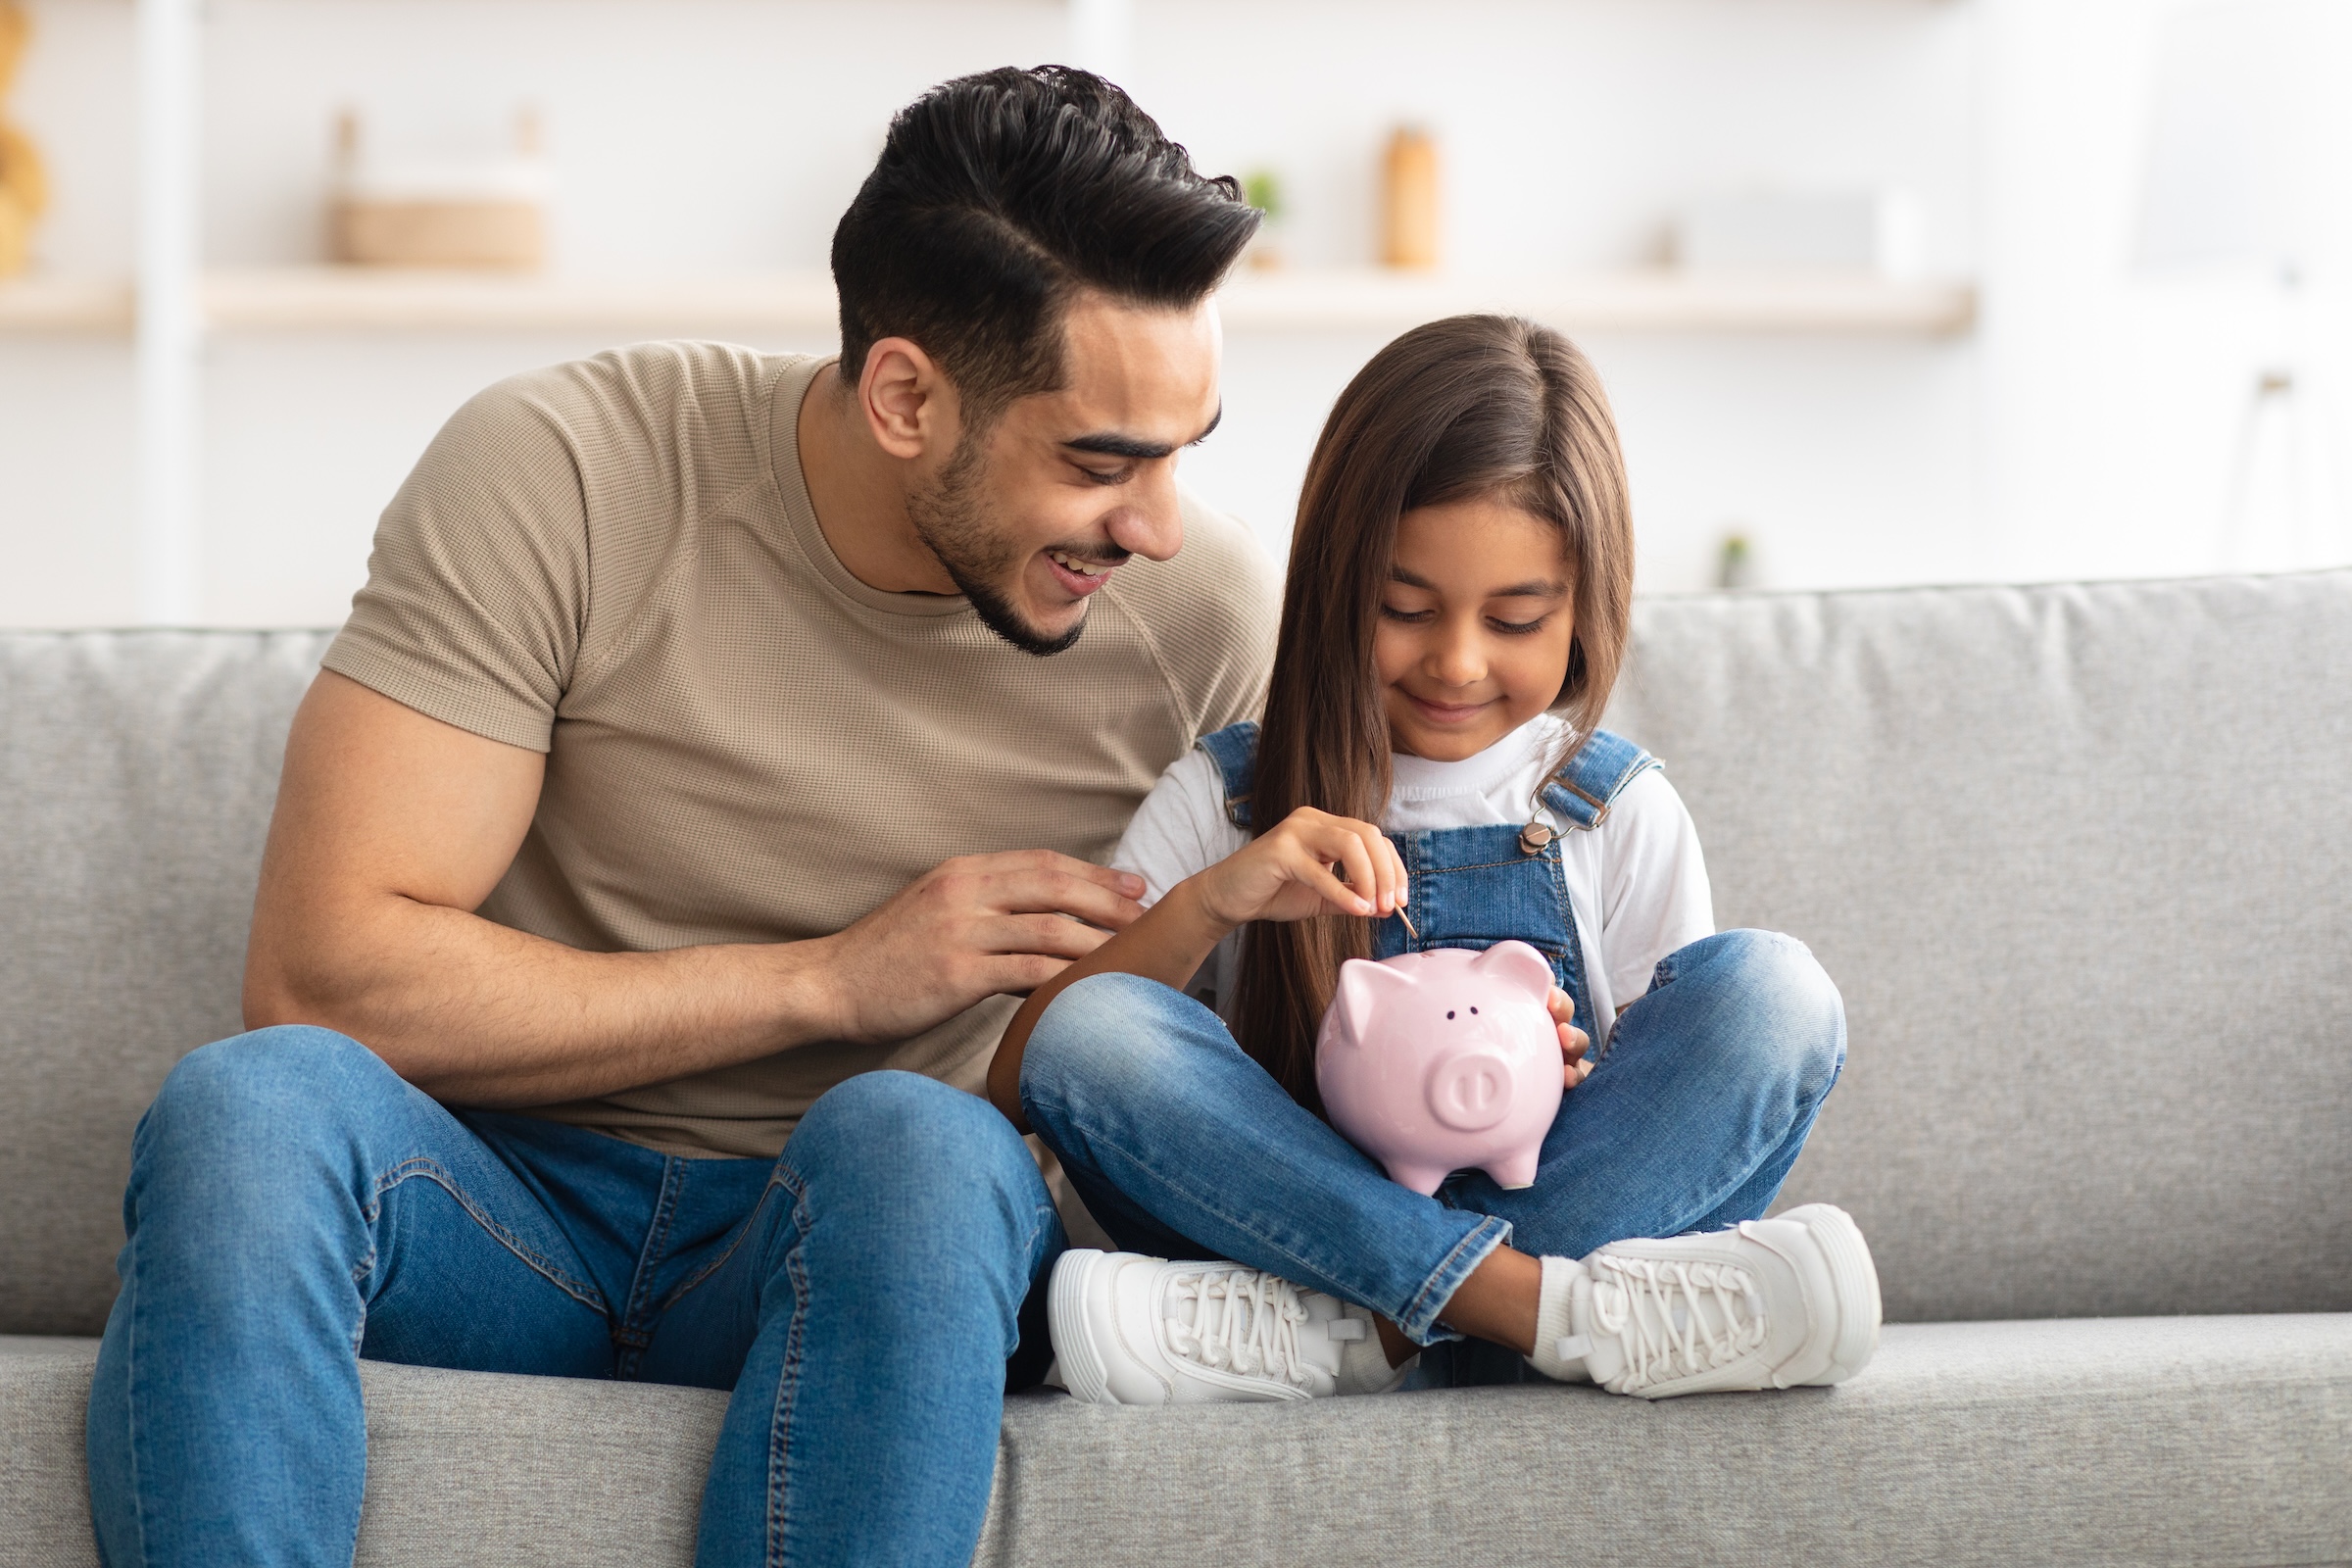


Teaching kids about money early is one of the most valuable things parents can do. Learning to earn, save, and make thoughtful spending choices helps children build confidence with money long before they manage it on their own.
Kids savings accounts in Idaho and Oregon, paired with local guidance and digital banking tools, give families a practical way to put those lessons into action. These six smart savings habits show how families can use Idaho First Bank’s savings offerings and digital banking tools to help raise a money-savvy kid.
There’s no single “right” age to open a savings account for a child. Some families might open one soon after a baby is born, while others wait until a child is old enough to understand what a balance is and why it matters. What matters most is opening the account early enough for kids to learn from real experiences, whether that’s birthday money tucked away, a first allowance, or a payment for mowing a neighbor’s lawn.
Requirements for a minor’s savings account vary by bank, but a parent or guardian typically opens the account with the child. Both will usually need identification and a Social Security number. It’s worth asking about the details up front, including whether an adult needs to be a joint owner and what happens to the account when the child reaches adulthood.
Families may also come across Trump Accounts, a federal program for children created under the One Big Beautiful Bill Act. These are tax-advantaged accounts with their own contribution limits, investment options, and withdrawal rules, and eligible children born between 2025 and 2028 may qualify for a one-time, $1,000 federal deposit. Because Trump Accounts work differently from a bank savings account, families can review the details through the IRS before deciding whether one fits their goals.
Regardless of whether or not a Trump Account is opened, a kids savings account at a bank can still serve as a place for everyday savings goals and money lessons. As for finding the best savings account for children, the answer depends on what a family values most. Take the following features into account:
Access to a local banker who can answer questions along the way is a plus, too. For more on getting started, see Idaho First’s original guide to kids savings accounts.
Saving “for the future” is a tough concept for a child to grasp without an end goal in mind. Saving for something specific, like a bike, a video game, or a family trip, can be simpler to understand and more motivating. Helping kids pick a goal, put a price on it, and plan how long it will take to reach it turns saving from an abstract idea into something with a finish line.
Start small. A goal that can be reached in a few weeks builds momentum, and each win makes the next, bigger goal feel more achievable. As kids get older, parents can introduce longer-term goals like a first car or college expenses, and talk through the difference in approach between saving for something in the short-term and saving for something later.
A dedicated account makes progress easy to see. Families can explore Idaho First’s personal savings accounts to find an option that fits their goals.
Opening an account is only the first step. The habit that really makes an impact is looking at it together. A quick monthly check-in, even just ten minutes at the kitchen table, gives kids a chance to see their balance grow, ask questions, and connect their choices to the results.
Digital tools make this easier for parents, too. With online and mobile banking, families can check balances, review recent transactions, and keep tabs on how a teen’s checking and savings accounts are being used, depending on how the accounts are set up. Security features like alerts and card controls add another layer of oversight as kids gain more independence. Idaho First’s online and mobile banking features are built to make that kind of regular check-in simple.
The goal isn’t to debate every purchase. It’s to make money a normal topic of conversation, so that by the time kids are managing larger amounts, talking about finances already feels natural.
Connecting effort to earnings is one of the most effective ways to teach kids about money. When kids earn wages for completing age-appropriate tasks, they start to understand that money comes from work, and that the things they want have a cost measured in effort as well as dollars.
Many families separate everyday responsibilities, like keeping a bedroom tidy, from extra jobs that can earn money, like washing the car or helping with yard work. That distinction helps kids see the difference between contributing to the household and working for a reward. However a family structures it, consistency is key. When kids know what to expect, they’re more likely to take ownership of what they earn and what they do with it.
Digital banking can keep this running smoothly. Parents with a checking account can set up recurring transfers to move allowance or earnings into a child’s savings automatically, instead of depending on someone to remember.
Once money starts coming in, the next question is where it should go. A simple approach is to divide earnings or allowance into categories, such as saving and spending, so that every dollar has a purpose. A child who gets $10 a week might put a portion toward a long-term goal and keep a portion to spend on an item or experience of their choice.
To start teaching kids the use of a checking and savings account in action, choose a checking account with a low-to-zero minimum opening deposit and a free debit card. Children have the ability to spend only the money available in their checking account using their debit card, while parents keep visibility through digital banking, offered as a feature with personal checking accounts. For teens ready for more independence, a checking account with a parent-controlled debit card lets them practice spending within a limit..
Over time, kids see the effect of splitting their money firsthand: The savings side grows steadily while the spending side teaches them to make choices within reason.
Numbers on a screen are useful, but there’s something about walking into a branch for a first bank account that makes it feel real. For many kids, meeting a banker, setting up an account, and making a first deposit is a memorable milestone.
A local bank can also make the process easier for parents. Since requirements vary by bank, it’s worth asking a banker directly about minimum balances, monthly fees, and fee waivers before opening a kids savings account. Having a local team on hand means those questions can be answered in person, and that families have someone to turn to as their needs change.
Visiting a branch also gives kids a chance to get comfortable speaking with a trusted professional. Asking a banker how an account works or what happens to their savings over time builds confidence in having real conversations about money. Those skills carry over as kids grow, so that by the time they’re opening a checking account or applying for a first loan, talking with a banker feels familiar instead of intimidating.
Families can find an Idaho First Bank location near them to start the conversation and learn more about the bank’s involvement in the communities it serves.
Raising a money-smart kid doesn’t require a big financial plan. It starts with a few small habits repeated often: opening an account, setting a goal, checking in regularly, earning, splitting, and building a relationship with a local bank. Families across Idaho and Oregon can visit an Idaho First Bank location to talk with a local banker about savings options for their kids and start building these habits today.